Part 2 of my notes on empirical asset pricing
The idea in one sentence
If markets absorb news quickly, then the price move right around an announcement tells you how much the market thinks the news is worth. An event study measures that move and strips out the part that would have happened anyway.
Post #1 explained why short windows are the cleanest setting: over a few days, errors in your “normal return” model are tiny. This post covers how the measurement is actually done.
Step 1: Pin down day 0
Everything is measured relative to the moment information became public, so getting day 0 wrong blurs the whole result.
The papers are careful about this:
- Acemoglu et al. (2016) found that news of Geithner’s nomination leaked around 3pm on Friday, November 21, 2008. So day 0 is only the last trading hour that day, measured with intraday (TAQ) data. The official announcement came Monday (day 1).
- Brown & Huang (2020) date each White House meeting by the first news article about it. If the article came out after the market closed, day 0 moves to the next trading day.
Many studies also start the window at day −1, to catch news that leaked slightly early.
Step 2: Estimate “normal” returns before the event
You need a prediction of what the stock would have returned without the news. The most common choice is the market model: 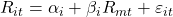
You estimate  and
 over an estimation window, then predict forward. Acemoglu et al. use 250 trading days (about a year) ending 30 days before the event.
Why the 30-day gap? If the estimation window runs up to the event, any leakage or run-up gets baked into “normal,” and you end up measuring the event against itself.
Simpler alternatives exist too. Brown & Huang use market-adjusted returns: just subtract the CRSP value-weighted market return. That’s the market model with  and
 . Over short windows the choice rarely changes the conclusion, which is exactly the point from post #1.
Step 3: Compute abnormal returns and add them up

The cumulative abnormal return (CAR) is the total surprise over the window. Brown & Huang find an average CAR of about 0.375% over [−1, +10] around White House visits. Geithner-connected firms show about 6% by the end of day 1.
How long should the window be? It’s a tradeoff:
- Shorter windows are cleaner, with less time for unrelated news to creep in.
- Longer windows capture slow price adjustment. Brown & Huang note that the market took about four trading days to fully price the 2016 election outcome (Wagner et al., 2018).
Reporting several windows, as both papers do, shows whether the effect holds up or reverses.
Step 4: Explain CARs across firms
An average CAR says that something happened. A cross-sectional regression says who it happened to: 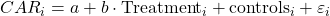
- Acemoglu et al.: Treatment is the number of meetings or board links with Geithner. Controls include cubics in size, profitability and leverage, since connected firms are bigger.
- Brown & Huang: after Trump’s 2016 win, firms whose executives had access to the Obama White House underperformed similar firms by about 70 basis points over three days, after controlling for campaign contributions, lobbying and government contracts.
The controls matter because treated firms usually differ from untreated firms in ways that also affect returns.
The trap: everyone shares the same event date
This is the pitfall people forget. Standard t-tests assume each firm’s abnormal return is independent. When all firms share day 0 (one nomination, one election), their returns move together because of everything else happening that day. The effective sample is much smaller than the number of firms, and naive standard errors are too small.
The papers handle it in different ways:
| Problem | Fix | Example |
|---|---|---|
| Residuals correlated across firms on the same day | Estimate the cross-firm covariance from pre-event returns and use it for standard errors | Acemoglu et al. |
| Firms in the same industry move together | Cluster standard errors by industry or date | Brown & Huang (industry); Bessembinder & Zhang (date) |
| Another big event lands in the same window | Drop firms exposed to it, or use a window that ends before it | Citigroup’s bailout came over the same weekend as Geithner’s nomination. Acemoglu et al. drop the 10% of firms most correlated with Citi and also report day 0 alone. |
| Is it really this event? | Run the same regression on non-event days or other events | Acemoglu et al. estimate the connection coefficient for every day from −10 to +10, and test rival Treasury candidates |
Events spread across many dates, like Brown & Huang’s 2,401 White House visits, suffer less, because unrelated market noise averages out across dates.
A nice check: only new information moves prices
If event studies measure surprise, the reaction should show up only when the information is actually news. Brown & Huang test this directly. When the White House released visitor logs, positive CARs appeared only for visits that hadn’t already been reported in the media (about 0.31% over [−1, +10]). Visits the market already knew about showed nothing. That’s the logic of an event study confirmed inside a single paper.
My checklist
- When exactly did the news become public? Get day 0 right, down to the hour if needed.
- Is the estimation window clean? It should end well before the event.
- How long is the window, and does the effect hold up or reverse?
- Do the firms share an event date? If so, are the standard errors adjusted for it?
- What else happened that week? Look for confounding news.
Next post: long-horizon returns. Why buy-and-hold abnormal returns over five years are so fragile, and how Bessembinder & Zhang rescue them.
References
Acemoglu, D., Johnson, S., Kermani, A., Kwak, J., & Mitton, T. (2016). The value of connections in turbulent times: Evidence from the United States. Journal of Financial Economics, 121(2), 368–391. https://doi.org/10.1016/j.jfineco.2015.10.001
Bessembinder, H., & Zhang, F. (2013). Firm characteristics and long-run stock returns after corporate events. Journal of Financial Economics, 109(1), 83–102. https://doi.org/10.1016/j.jfineco.2013.02.009
Brown, J. R., & Huang, J. (2020). All the president’s friends: Political access and firm value. Journal of Financial Economics, 138(2), 415–431. https://doi.org/10.1016/j.jfineco.2020.05.004
Campbell, J. Y., Lo, A. W., & MacKinlay, A. C. (1997). The Econometrics of Financial Markets. Princeton University Press.
Fama, E. F. (1991). Efficient capital markets: II. Journal of Finance, 46(5), 1575–1617.
Wagner, A. F., Zeckhauser, R. J., & Ziegler, A. (2018). Company stock price reactions to the 2016 election shock: Trump, taxes, and trade. Journal of Financial Economics, 130(3), 428–451.